Pre-Approval Auto Financing Guide for New Jersey Buyers
Applying for auto financing before visiting a dealership in New Jersey allows you to secure a specific interest rate and loan amount, giving you negotiating power and a clear budget. This process, known as pre-qualification or pre-approval, involves a soft credit check that does not impact your score. This guide explains how to gather documents, compare lenders, and use your pre-approval at Team Welsh Jeep Chrysler to streamline your purchase. For additional details, review the teamwelshjeepchrysler com.
Understanding Pre-Approval vs. Pre-Qualification
Many buyers confuse pre-qualification with pre-approval. Pre-qualification is an initial estimate based on self-reported income and credit history. It is not a guarantee of funding. Pre-approval is a formal commitment from a lender to lend a specific amount at a specific interest rate, contingent on final verification. For a smooth dealership visit, pre-approval is the gold standard. It tells the sales team exactly what you can afford, preventing them from steering you toward vehicles outside your budget. For additional details, review the Frequently Asked Questions.
Why Pre-Approval Matters in New Jersey
New Jersey has a competitive auto market. Having a pre-approved loan from a bank or credit union allows you to compare the dealership's in-house financing against your external offer. This competition often leads to better terms. At Team Welsh Jeep Chrysler, our finance team is accustomed to working with pre-approved customers. We can often match or beat external rates, but only if you have a concrete offer in hand. For additional details, review the About.
Essential Document Checklist
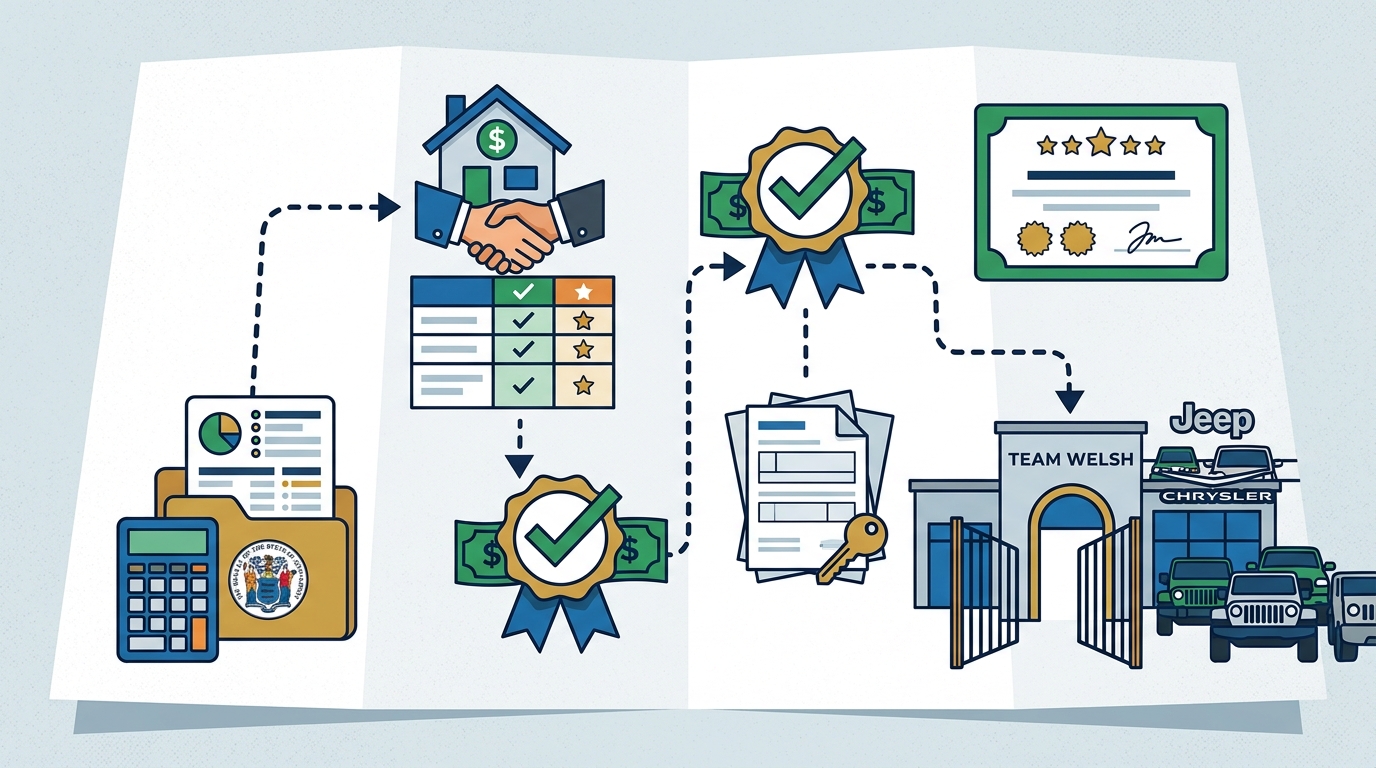
Lenders require proof of identity, income, and assets. Gathering these documents before applying saves time and prevents delays. Keep digital copies in a secure folder and physical copies in a binder for your dealership visit.
Identity and Contact Information
- Government-issued photo ID (Driver's License or Passport)
- Social Security Number
- Current address history for the last two years
Income Verification
- Most recent two pay stubs (for W-2 employees)
- Year-to-date profit and loss statement (for self-employed)
- Most recent two years of tax returns (for self-employed or business owners)
Asset and Debt Information
- Bank statements showing savings or checking balances
- List of current debts (credit cards, student loans, mortgages) with monthly payments
- Details of any existing vehicle loans you intend to pay off
Loan Terms Comparison: How to Evaluate Offers
| Term | Definition | Why It Matters |
|---|---|---|
| APR (Annual Percentage Rate) | The yearly interest rate charged on the loan. | Lower APR means less interest paid over the life of the loan. |
| Loan Term | The length of the loan in months (e.g., 60, 72, 84). | Longer terms lower monthly payments but increase total interest cost. |
| Down Payment | The upfront cash paid toward the vehicle. | Higher down payments reduce the loan amount and may lower the APR. |
| Prepayment Penalty | A fee charged if you pay off the loan early. | Most auto loans have no penalty, but always verify. |
| Gap Insurance | Coverage for the difference between loan balance and vehicle value. | Essential if you finance more than the car is worth. |
Calculating Total Interest
To compare two offers, calculate the total interest paid. Multiply the monthly payment by the number of months, then subtract the original loan amount. The difference is the total interest. A loan with a slightly higher monthly payment but a shorter term often results in significantly lower total interest.
Credit Score Impact and Lender Requirements
Your credit score is the primary factor determining your interest rate. Credit score is a three-digit number ranging from 300 to 850 that predicts the likelihood of repaying a debt. Lenders use this score to categorize risk. In New Jersey, most auto lenders require a minimum score of 620 for standard financing. Scores below 600 may qualify for subprime loans with higher interest rates.
Soft vs. Hard Inquiries
When you apply for pre-approval, ask the lender if they perform a soft or hard inquiry. A soft inquiry does not affect your credit score. A hard inquiry may lower your score by a few points. Multiple hard inquiries within a short period (14 to 45 days) are often treated as a single inquiry by credit bureaus when calculating auto loan scores. However, to be safe, limit your applications to two or three lenders.
Using Pre-Approval at the Dealership
Steps for a Smooth Visit
- Bring your pre-approval letter and all documents listed in the checklist.
- Inform the sales team of your budget and pre-approved amount.
- Negotiate the final terms based on the total cost, not just the monthly payment.
Common Mistakes to Avoid
Buyers often make errors that cost them thousands of dollars. Avoid these common pitfalls:
- Applying to too many lenders: This can clutter your credit report and lower your score.
- Ignoring the total cost: Focus on the total interest paid, not just the monthly payment.
- Not reading the fine print: Check for prepayment penalties and mandatory insurance requirements.
- Assuming the dealership has the best rate: Always compare with external lenders.
Key Takeaways
- Pre-approval provides a guaranteed rate and amount, giving you negotiating power.
- Gather all income and asset documents before applying to avoid delays.
- Compare APR, loan term, and total interest, not just the monthly payment.
- Use a soft credit check for initial pre-qualification to protect your score.
- Bring your pre-approval letter to Team Welsh Jeep Chrysler to compare offers.
- Limit hard inquiries to two or three lenders within a 45-day window.
- Verify if the loan has a prepayment penalty before signing.
Frequently Asked Questions
Does pre-approval guarantee I will get the loan?
Pre-approval is a strong indication that you will be approved, but it is not a final guarantee. The lender will perform a final credit check and verify your income before funding the loan. However, it is much more likely to be approved than a standard application.
Will checking my credit for pre-approval lower my score?
It depends on the type of inquiry. A soft inquiry does not affect your score. A hard inquiry may lower it by a few points. Most auto lenders treat multiple hard inquiries within a 45-day period as a single inquiry for auto loan scoring purposes.
Can I use a pre-approval from a credit union at a dealership?
What if my credit score is below 600?
You may still qualify for financing, but the interest rates will be higher. Consider adding a co-signer with good credit or making a larger down payment to improve your chances of approval.
How long does the pre-approval process take?
Online pre-qualification can take minutes. Formal pre-approval with document verification may take one to three business days. It is best to apply at least one week before your dealership visit. Learn more: teamwelshjeepchrysler com.